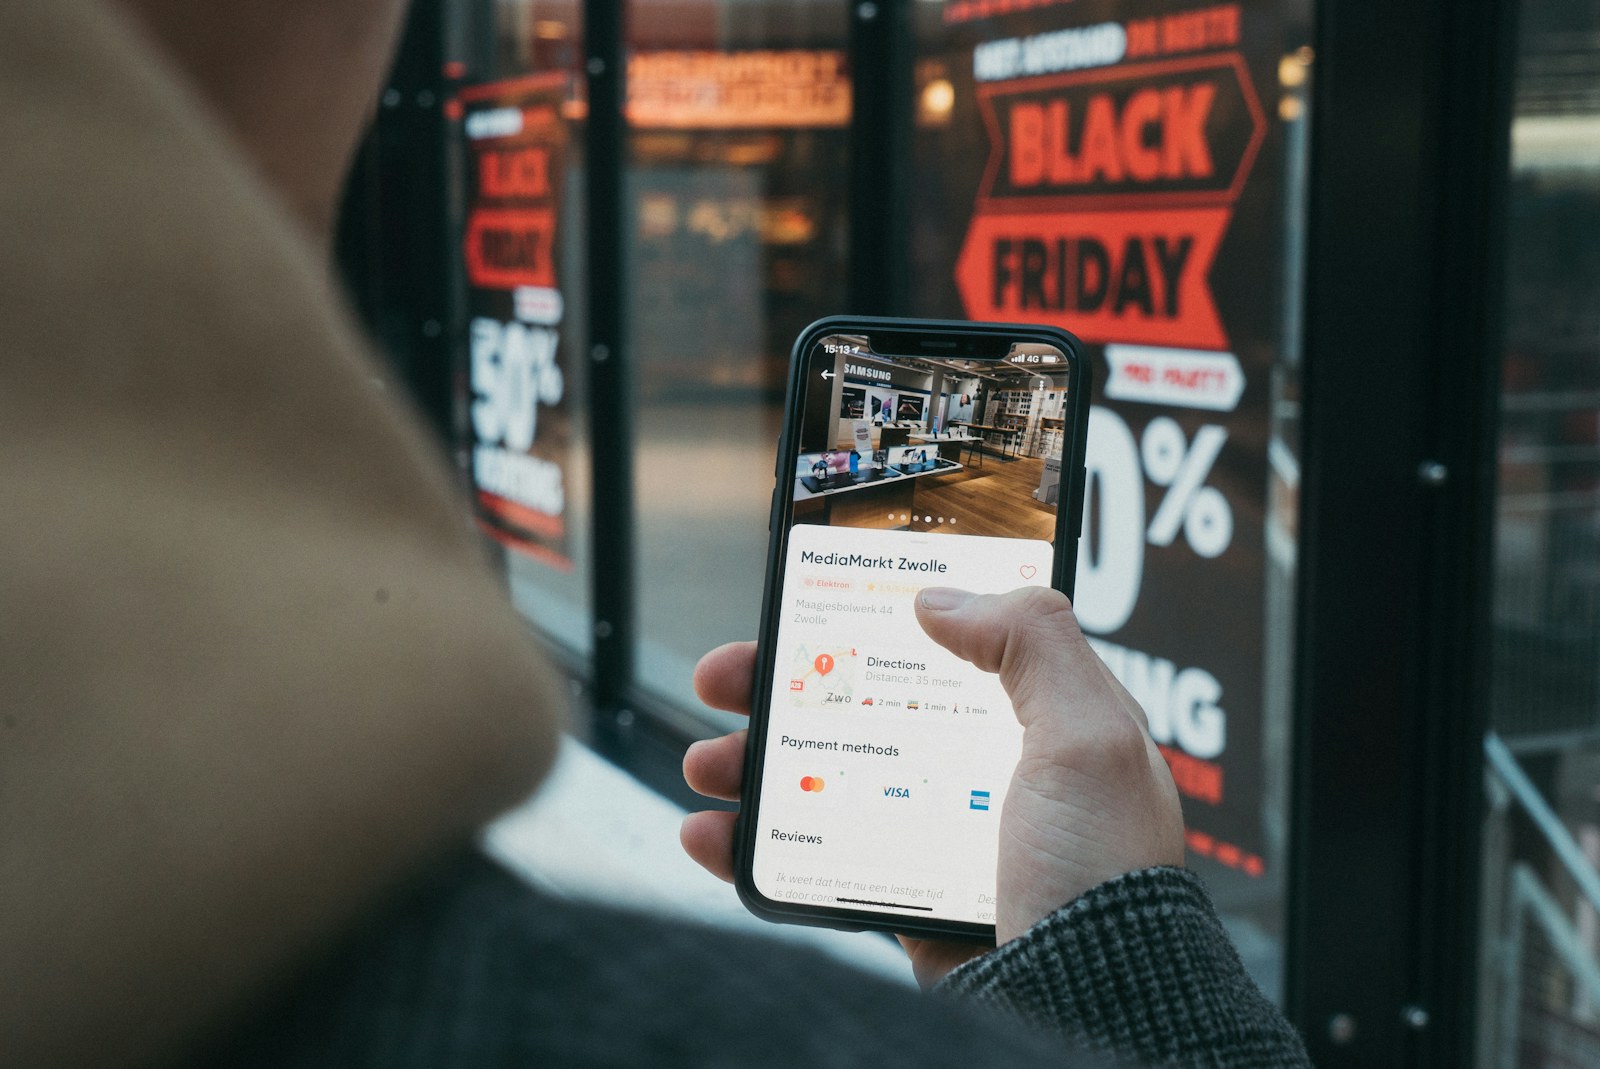
Phones have quietly become the default wallet. According to the Federal Reserve’s 2025 Diary of Consumer Payment Choice, U.S. consumers made an average of 11 payments per month with a mobile phone in 2024, up from four in 2018. Among younger shoppers the shift is even sharper: adults aged 18 to 24 used their phones for 45% of all payments.
Checkout pages built around a typed-in card form are falling behind that habit. Ecommerce payments now decide more sales than most product pages do. Digital wallets and Pay by Bank target two separate weak points: the friction of manual entry and the cost of card processing.
What Slows Down Ecommerce Payments Today?
Most checkout problems come from three sources: too much typing, too little trust, and options that don’t match the shopper. Each one costs conversions in a different way, and the fixes differ as well.
The Hidden Cost of Manual Card Entry
A standard card form asks for the card number, expiry date, security code, name, and billing address. On a small screen, every extra field is another chance for a typo, a validation error, or an abandoned order.
The pressure keeps growing. The same Federal Reserve study found that 23% of consumer purchases and peer-to-peer payments were made remotely in 2024, a share that has increased each year since 2021.
Why Card Fees Eat Into Margins
Every card transaction carries interchange and scheme fees. For high-ticket or low-margin categories, those percentages turn into a serious line item in ecommerce payment processing. Many merchants never see the true cost, because fees are bundled into a single blended rate.
How Do Digital Wallets Improve the Checkout?
Digital wallets improve checkout by replacing a long form with one tap and a biometric check. Apple Pay, Google Pay, and PayPal already store the shopper’s card and address, so the store receives the details it needs in seconds. For mobile ecommerce payments, few changes deliver results this quickly.
Key Benefits of Wallets for Ecommerce Payments
Wallets solve the mobile problem more directly than any form redesign. Their main advantages include:
- Speed: one-tap checkout removes nearly all manual fields.
- Security: tokenization sends the merchant a device-specific token instead of the real card number.
- Authentication: Face ID or a fingerprint confirms the buyer and lowers fraud risk.
- Familiarity: shoppers trust buttons they already use on other sites.
How to Add Wallets to an Online Store
The quickest route is a gateway that bundles several wallets into one integration, such as Stripe or Mollie. Wallet buttons belong at the top of checkout and, ideally, on cart and product pages too. Only wallets the device supports should appear, since a button that fails on tap damages trust.
Pro Tip: Test wallet flows on physical phones rather than emulators. Address handoffs, discount codes, and tax recalculation often behave differently on real devices.
Note: most wallets run on card rails, so they lift conversion but rarely reduce fees.
What Is Pay by Bank and Why Does It Matter?
Pay by Bank is an account-to-account (A2A) payment that moves money directly from the shopper’s bank account to the merchant’s, with no card involved. The customer selects a bank, approves the amount in the banking app, and returns to the store.
How Fast Are Bank Payments Growing?
Bank payments are growing fast enough to count as mainstream in several markets. Open Banking Limited’s seventh Impact Report recorded roughly 31 million open banking payments in the UK in March 2025, equal to 8% of all Faster Payments. Volumes have kept up year-on-year growth of about 70%.
The trend reaches beyond the UK. Brazil’s Pix has run since November 2020, and the US FedNow Service launched in July 2023. For ecommerce payments, this means a growing share of shoppers already know how to approve a bank transfer in seconds.
Cost and Security Advantages
Bank payments bypass card networks, so they also avoid interchange and scheme fees. Banking credentials stay with the customer’s bank and never reach the merchant’s servers. Lower costs and a smaller fraud surface rarely arrive together in ecommerce payments, which is what makes this method stand out.
Steps to Implement Pay by Bank
- Choose an aggregator. Providers such as Stripe or Solidgate connect to many banks and local real-time rails through one integration.
- Place the button prominently. “Pay by Bank” should sit beside card and wallet options, not inside a hidden menu.
- Optimize the redirect. The jump to the banking app and back must be fast and mobile-friendly.
- Explain security in plain words. A short line confirming that login details stay with the bank reduces hesitation.
Important: A2A payments do not include the card-network chargeback process. Refund terms should be clearly stated at checkout.
Wallets vs. Pay by Bank: Which Fits Better?
Neither method replaces the other in ecommerce payments; each solves a different problem. The comparison below includes traditional cards as a baseline.
| Factor | Cards | Digital wallets | Pay by Bank |
|---|---|---|---|
| Checkout speed | Slow (manual entry) | Very fast (one tap) | Fast to moderate (bank redirect) |
| Typical fees | Interchange + scheme fees | Usually card-level fees | Often lower, no card fees |
| Data the merchant receives | Card number | Token | No card data |
| Chargebacks | Card-network process | Card-network process | No card scheme |
| Strongest use case | Universal fallback | Mobile shoppers | High-value orders |
Choosing the Right Ecommerce Payment Solution
The right ecommerce payment solution supports cards, wallets, and bank payments through one integration and one dashboard. Fragmented ecommerce payments setups complicate reconciliation and hide which methods actually perform. Better providers also order options by country and device, so each shopper sees familiar choices first.
What Should Be Measured After Launch?
Performance should be measured per payment method, not as one blended average. The core metrics are:
- Checkout conversion rate by device
- Payment success rate for each method
- Processing cost per completed order
- Dispute and refund rates
A simple formula makes comparisons easier: Effective cost per order = total fees for a method ÷ completed orders through that method. Reviewing ecommerce payments data this way shows where bank payments save money and where wallets lift conversion.
Frequently Asked Questions
Are digital wallets safe for online stores?
Yes, digital wallets are among the safest ways to accept online payments. Tokenization means the merchant never receives the actual card number. Biometric confirmation adds a layer that a stolen password cannot bypass.
Does Pay by Bank work for international customers?
Pay by Bank works best in markets with established open banking or real-time bank rails, such as the UK, the EU, and Brazil. Aggregators extend coverage to more countries, but availability varies. Local support should be checked market by market before launch.
Can wallets and Pay by Bank lower payment costs?
Pay by Bank can lower costs, while wallets usually cannot. Bank transfers bypass card networks and their fees, but most wallet transactions are still processed as card payments. Wallets earn their place through higher conversion rather than savings.
How many payment methods should a checkout display?
A checkout should display only the few methods most relevant to each shopper. Showing options based on location and device keeps the page clean while still offering familiar choices. Too many buttons slow decisions and can reduce conversion.
What is the first step to improve ecommerce payments?
The first step is auditing the current checkout on a mobile phone. Counting form fields, timing the flow, and noting where shoppers drop off reveals which upgrade matters most. Wallets usually fix speed first, and Pay by Bank addresses cost next.
Terry Clark is the Publisher and Content Director of 365 Retail, with more than a decade of experience covering retail design, technology innovations, store openings and the wider retail industry. He also works closely with leading retailers, suppliers, agencies, events and industry awards across the UK.